Credit cards
Compare benefits, fees and who can apply, across 153 cards from 16 issuers
ⓘ Card facts come from each issuer’s published terms. Check the latest conditions with the bank before applying.
Search by purpose
Start with your income and savings
Search by popular feature
Pick what matters to you and the ranking below filters itselfCredit card ranking
More conditions
Which card pays you back most?
Enter your monthly spend per category and see what each card gives back in a yearFor now there are 21 cards to compare. We’ll add more cards once we have complete, accurate details from the banks.
Estimates from the terms each bank publishes, as of the date shown for each card. Points are valued at the bank’s published redemption rate. Shop-only bonuses, sign-up offers and per-slip minimums are not counted, and promotions stop counting after they end. The fee is the one from year 2, after any waiver. Check the current terms with the bank before applying.
Which card pays you back most?
Enter what you spend a month, then tap the button Taggy is comparing the cards
Credit card search
Cards users like, by use
Picked from user reviews · terms change, check with the bank before applying💳Starter & cashbackEasy to get, low fees, money back on everything
-
1
 ttb so smartttb
Liked forSimple cashback and no annual fee; users name it as a favourite
CheckSome categories earn no cashback
Source: User comments -
2
 UOB ONEUOB
Liked forSuits everyday spending: BTS/MRT, Grab, convenience stores and coffee
CheckCheck the cashback cap, payment channels and the annual fee
Source: Usage review -
3
 Krungsri NOW PlatinumKrungsri
Liked forOnline shoppers see real cashback; users report getting it back on Shopee
Check5% back per ฿500 on each slip, up to ฿300 a month
Source: User experience
🛍️Shopping & lifestyleOnline shops, dining and the stores you use
-
1
 KTC VISA PlatinumKTC
Liked forNo annual fee, good dining and shopping deals, points never expire
CheckValue depends on using the deals and redeeming points
Source: User review -
2
 UOB PreferredUOB
Liked forDeal hunters stack it with dining and online discounts
Check15% back is capped at ฿30 per shop per month under current terms
Source: Usage example -
3
 KBank–ShopeeKBank
Liked forUsers like the perks and convenience for regular Shopee buying
CheckK Point, Shopee Coins and discount codes each have their own terms
Source: User review
✈️Travel & premiumMiles, lounges and travel cover
-
1
KrungsriKrungsri JCB PlatinumKrungsri
Liked forMade for Japan lovers, shops and travel alike, though some rarely use it
CheckRecently revamped: check the new benefits and do not confuse it with Ultimate
Source: Multi-card review -
2
 ttb absolutettb
Liked forComparison reviews rate its overseas fees and lounges
CheckLounge access now depends on approval year and customer status
Source: Comparison review -
3
 UOB PremierUOB
Liked forReviews praise its airport perks, especially Miracle Lounge
CheckNew cardholders from 1 Aug 2026 get lounges only after meeting the spend for the next year
Source: Benefit review
Swipe for the other groups
Bank wealth tiers: what your deposits reach
Deposits plus investments with that institution · as of 3 Nov 2026Pick a balance, or enter your deposits above, to highlight your tier at each bank
 KBank
- The Premier฿2–10M
- THE WISDOM฿10–30M
- WISDOM INFINITE฿30–50M
- Private Banking฿50M+
 Krungsri
- Prime฿1–5M
- Exclusive฿10M+
 KKP
- Dime!up to ฿2M · KKP’s investing app
- Edge฿2–30M
- Private Wealth฿30M+
 SCB
- Prime฿2–10M
- First฿10–50M
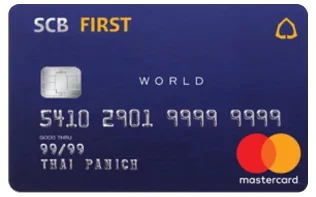
- Private Banking฿50M+ · SCB Julius Bär from ฿100M
 ttb
- Reserve Signature฿5–30M
- Reserve Infinite฿30M+
 Bangkok Bank
- Bualuang Exclusive฿3M+
 CIMB Thai
- Preferred฿3–10M
- Preferred Elite฿10–30M
- Private Wealth฿30M+
 UOB
- Wealth Banking฿2–10M
- Privilege Banking฿10–50M
- Privilege Reserve฿50M+
 Citibank
- Citi Priority฿1–5M
- Citigold฿5–10M
- Citigold Preferred฿10–50M
- Citigold Elite฿50M+
 Krungthai
- Precious฿2–10M
- Precious Plus฿10–50M
- Precious Plus Infinite฿50M+
 Finnomena
- Exclusive฿0.5–2M
- Private Wealth฿2–10M
- Private Banking฿10M+
 HSBC
- Premier฿5–30M · approximate
- Jade฿30M+ · approximate
 TISCO
- Platinum Wealth฿5–20M
- Private Wealth฿20M+
Entry tierMiddle tierTop tier (crown)Your balance reaches this tier
Source: PriceTag TH · ranges are approximate, check the current terms with the bank
Read before you apply
All articles เจอรายการรูดที่ไม่ได้ทำ ต้องทำอะไรก่อน?เจอรายการรูดบัตรเครดิตที่ไม่ได้ทำ ต้องทำอะไรก่อน ระงับบัตร แจ้งผู้ออกบัตร เก็บหลักฐานอะไร และ 4 คำถามที่ต้องได…
 จ่ายขั้นต่ำกับจ่ายเพิ่มทุกเดือน ดอกเบี้ยต่างกันเท่าไร?จ่ายขั้นต่ำกับจ่ายเพิ่มทุกเดือน ดอกเบี้ยบัตรเครดิตต่างกันเท่าไร เทียบหนี้ 50,000 บาทสามวิธีจ่าย พร้อมขั้นตอนที…
 เงินคืน คะแนน หรือไมล์ แบบไหนคุ้มกับยอดที่คุณจ่าย?เงินคืน คะแนน หรือไมล์ แบบไหนคุ้ม แปลงผลตอบแทนเป็นเงินบาท ด้วยตัวอย่าง 30,000 คะแนน KTC ใช้ลดค่าใช้จ่ายหรือโอน…
 รูดบัตรต่างประเทศ เลือกจ่ายเป็นบาทหรือสกุลท้องถิ่น?รูดบัตรเครดิตต่างประเทศ เลือกจ่ายเป็นเงินบาทหรือสกุลท้องถิ่นถูกกว่า รู้จัก DCC พร้อมตัวอย่างคำนวณจากยอดซื้อ 10…
Classic, Gold, Platinum: what changes
Mostly minimum income and limit. Perks depend more on the card than the tier: some free Platinum cards pay more cashback than a paid Signature card. If you don’t use lounges or miles, there’s no rush to move up.
Paying the minimum, and 16% interest
Pay only the minimum and the rest is charged up to 16% a year from the day you spent. That wipes out any 1–5% cashback. Set a full-balance auto debit.
How much can your limit be?
The Bank of Thailand caps the total limit across all your cards by monthly income: under ฿30,000 up to 1.5×, ฿30,000–50,000 up to 3×, and ฿50,000 or more up to 5×.
Credit card basics for beginners
Worth reading before your first card, or your next
The credit card basics you should know
Summarised from bank terms and Bank of Thailand rules. Updated Nov 2026
Classic, Gold and Platinum: the differences
Cards go from Classic to Gold, Platinum, Signature (World on Mastercard) and Infinite (World Elite). Higher tiers ask for more income and give bigger limits, with perks such as airport lounges, travel cover and concierge, but the annual fee usually rises too.
In Thailand many Platinum cards accept ฿15,000 income and charge no fee, so the tier alone says little about value. Check the benefits where you actually spend first, then the rest.
Card networks: Visa, Mastercard, JCB and others
Visa and Mastercard are accepted almost everywhere, in Thailand and abroad. JCB is popular in Japan and often has Japanese shop discounts. American Express is strong on travel and dining but accepted in fewer shops. UnionPay is handy in China.
The network does not set the cashback or points; the issuing bank does. The same card on two networks usually earns about the same.
Card benefits
Common benefits are travel accident cover when the fare is paid by card (automatic on some cards), airport lounges, 0% instalments at partner shops and dining or cinema discounts.
Before you count a benefit as value, check whether it needs registration, a minimum spend or has a yearly limit.
Paying your bill: in full, the minimum, or instalments
Pay in full by the due date and there is no interest, giving roughly 45–55 interest-free days from the purchase.
Pay only the minimum and the rest is charged up to 16% a year from the posting date, many times more than any cashback. 0% instalments split the price into equal monthly payments on the shop’s terms. An automatic full-balance debit is the safest setting.
How big a limit can you get?
The Bank of Thailand caps the total limit across all your cards by monthly income: under ฿30,000 up to 1.5×, ฿30,000–50,000 up to 3×, and ฿50,000 or more up to 5×.
Applying and getting approved
The minimum income is ฿15,000 a month; some banks accept a pledged deposit instead. You need your ID card, a payslip or salary certificate, and 3–6 months of bank statements.
Banks also check your credit bureau record. Approval takes from a few days to about 3 weeks, and applying for several cards at once can make it harder.
Cash advances
A cash advance usually costs a fee of about 3% of the amount, and interest starts the same day with no interest-free period. Use it only when you have to.
Using your card abroad
Most Thai banks charge about 2.5% on foreign-currency spending, network share included. A card with a lower rate, or extra rewards abroad, pays off for frequent travellers.
If the terminal offers baht or the local currency, always choose local: paying in baht (DCC) usually gets a worse rate. Visa and Mastercard work almost everywhere, JCB suits Japan, and check overseas use is switched on in your bank app before you fly.

